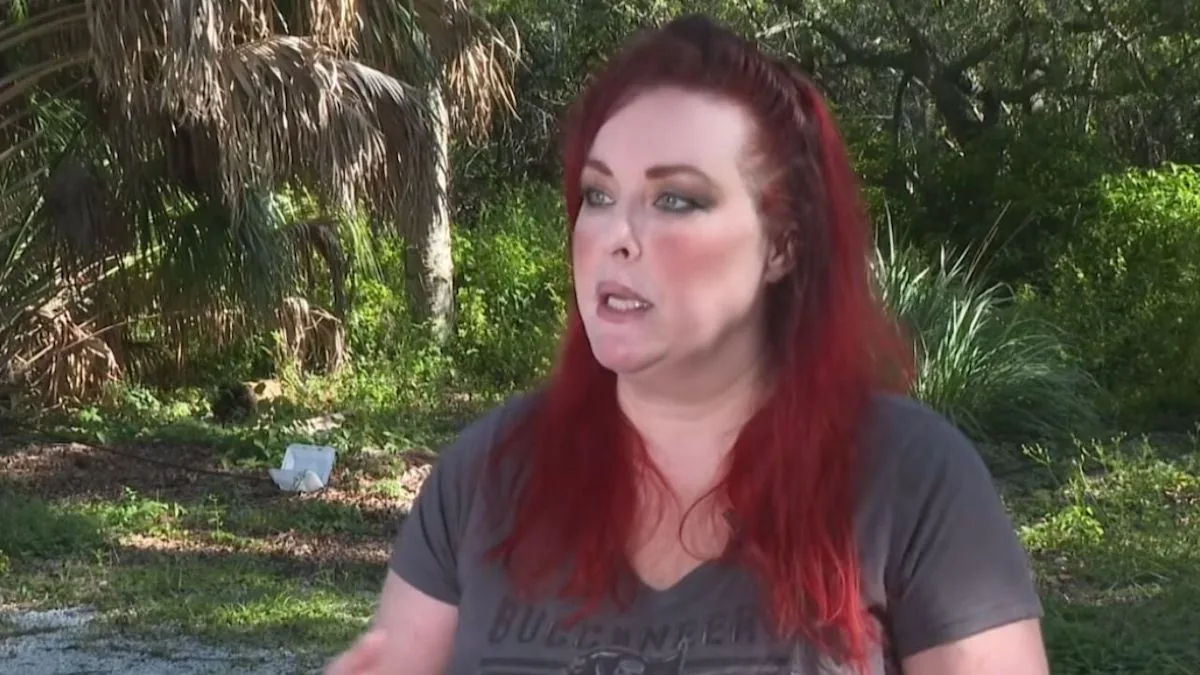
WASHINGTON, DC — Kara Windeler says rising health insurance costs are threatening the coverage she depends on for specialists, medications and continuing treatment. She has lived with chronic health problems since she was six weeks old, and she told CNN that her care has become expensive enough to reshape nearly every part of her finances.
Windeler said she sold the home she had owned for 17 years in 2024 so she could keep paying medical bills. That sale gave her a temporary cushion, but she said those funds have now been used up. After reviewing what was billed to her insurer during 2025, she said the total topped $200,000.
Why a cheaper plan could create bigger problems
Windeler’s biggest worry is that a lower-premium plan could come with a much narrower network of doctors and services. She said her chronic autoimmune conditions require several specialists, ongoing testing and regular medications, and she has not assumed those providers or treatments would be covered in a less expensive policy.
That means the decision is not just about monthly premiums. For someone with complicated long-term illnesses, changing plans can mean changing doctors, changing prescriptions and reworking treatment at a time when stability matters. Windeler told CNN that trying to replace the care she already has could force her to start over with specialists who may not know her medical history.
She also said treatments for autoimmune conditions do not always work right away, which makes a switch even harder. In her words, she has reached the point where she is “liquidating little pieces” of her life to keep paying for care.
Enhanced ACA tax credits ended after 2025
The higher premium assistance many Marketplace enrollees received in recent years ended Dec. 31, 2025. HealthCare.gov says returning customers who still qualify for savings in 2026 are likely to see higher premiums than they paid before.
The enhanced subsidies were created under the American Rescue Plan in 2021 and later extended through 2025 by the Inflation Reduction Act. They increased help for people already eligible for Marketplace subsidies and temporarily removed the income cap that had limited premium-tax-credit eligibility at 400% of the federal poverty level.
That change helped many households afford coverage, but its expiration is now affecting what people pay at enrollment. For some consumers, especially those with ongoing medical needs, the loss of that extra support may determine whether they stay in the same plan or shop for a cheaper one.
KFF says average premiums and deductibles climbed
Health policy group KFF found that the average monthly net premium payment among Marketplace consumers rose 58% in 2026, increasing from $113 in 2025 to $178. That jump shows how quickly out-of-pocket costs can change when subsidies shrink and plan choices shift.
KFF also reported a move toward bronze plans, which usually have lower monthly premiums but higher cost sharing when people actually use care. Bronze plans accounted for 40% of Marketplace selections in 2026, up from 30% the year before.
The organization found that average deductibles also increased by $1,027, from $2,759 to $3,786. KFF said much of that increase reflected consumers moving away from lower-deductible silver plans and into plans that leave them with more costs before coverage fully kicks in.
How HealthCare.gov says shoppers should compare plans
For people with chronic conditions, a lower premium does not always mean a lower total bill. A plan with a small monthly payment may still cost more over the year if it has a large deductible, limited drug coverage or a narrow provider network.
HealthCare.gov advises shoppers to compare plans using their doctors, hospitals and prescriptions. The marketplace also links to each plan’s provider directory, drug list and Summary of Benefits and Coverage so consumers can see what is included before they switch.
The federal site says people should verify provider participation through an insurer’s directory or by contacting the insurer directly. HealthCare.gov also recommends checking with the medical office itself, since directories do not always reflect the latest network changes.
Income updates and appeals can affect assistance
HealthCare.gov also tells Marketplace customers to update expected household income and other application details, since those numbers affect eligibility for premium tax credits and the amount of help they receive. A change in income can alter what a person pays each month as well as what assistance is available.
Consumers who believe the Marketplace made the wrong decision about their eligibility or financial aid may be able to appeal. HealthCare.gov says people generally have 90 days from the date of an Eligibility Notice to request an appeal.
For Windeler, the problem is immediate and personal, but the guidance applies broadly to other Marketplace enrollees facing the same reset in coverage costs. As the open enrollment choices change, the practical question for many households is no longer just which plan is cheapest, but which one can actually support ongoing care.